TDC Scrap Outlook — Q3 2026 Review and Q4 Outlook
Corrected 6 October 2026 (v2): the landed-cost section originally used 40HC freight by default; Pakistan-bound scrap ships in 20FT containers, which are now used throughout, moving US East Coast landed cost from $403.89 to $400.04/t, freight share from 10.6% to 9.8%, the gap to the published CFR Port Qasim shredded price from ~$14 to ~$18/t, and October’s freight impact from +$8.50 to +$2.60/t. No other figure changed.
Data to 30 September 2026. Every figure below is a publisher print, an official statistic, or a TDC calculation from them; methodology and sources at the end. TDC Ventures trades and indents the materials discussed.
Headline findings
- If you buy scrap in Pakistan: the price you pay did not follow Turkey. the published CFR Port Qasim shredded price (Fastmarkets’ index) ended the quarter at $417.72/t, inside a $390–421 band it never left, while Turkey’s benchmark rose $19.50–25.00/t to $419–421. Offers at $440–445 found no buyers for four straight weeks; bids held $415–418. The physical anchor, not the offer, is the price.
- If you sell from the UK, Europe or the US East Coast: your reference prices rose with Turkey — Rotterdam HMS FOB +$22.09 to $359.28, UK HMS FOB +$16.08 to $360.05, FOB New York +$6.00 to $349.00 — but the destination that matters for containers did not. The spread between Pakistan and Turkey shredded went from about +$27 to −$3.28 in six weeks, the first time Qasim priced below Turkey since April.
- What a tonne really costs delivered: US East Coast HMS landed into Port Qasim at about $400/t on September freight and standard terms — $349 FOB, $39.20 ocean freight per tonne in a 20FT box at 25 t (scrap into Pakistan moves in 20FT), documentation and financing. Freight was only 9.8% of the landed number. US material undercut the published CFR Port Qasim shredded price by roughly $18/t before quality adjustment.
- Freight did not drive this quarter — October’s board says it may drive the next. New York–Qasim held at $980 per 20FT all September; the October rate sheet (after our cutoff) shows $1,045, about +$2.60/t on landed cost.
- Turkey’s rally looks cyclical, not a new level. Shredded sat exactly $20/t over HMS for the whole quarter, rebar FOB rose in step (+$37.50 to $627.50), and the move coincided with October-shipment restocking. Our base case for Q4 is a Turkey plateau at $412–428 and a range-bound Pakistan at $410–422 unless local demand improves.
Executive summary
What happened. Everything upstream of Turkey — Rotterdam, the UK, the US East Coast — repriced upward from late August, and Turkey’s two shredded benchmarks finished the quarter at their highs. Pakistan, the destination that matters most for containerized scrap, stayed inside a thirty-dollar band for the entire quarter and finished below Turkey.
Why. Not freight: our forwarder quotes for New York–Qasim were $980 per 20FT every week of September. Not the rupee: flat. Pakistani finished-steel demand stayed slow, buyers kept their bids near $415–418, and sellers’ offers in the $440s went unconverted week after week. Turkey, meanwhile, was restocking for October shipment, and its mills passed the cost through to rebar.
What it means for you. Buyers in Pakistan: the index tracks deals, not offers; there has been no reason to pay above the physical anchor and there still isn’t. Sellers into South Asia: pricing off Turkey’s rally overstates what Qasim will pay; US East Coast HMS lands at about $400/t, which is the competition. Traders: freight was quiet this quarter and is the thing to re-price first in Q4 — in the right box.
What to watch. A Kallanish Turkey shredded print above $428 or below $412 by 31 October; whether Qasim tracks Turkey’s October direction within three weeks; the New York–Qasim rate now that October’s sheet has stepped up.
Our record. Twelve calls resolved on the two core markets this quarter; the full scored record, misses included, is on the Track Record page and summarised in Section 10.
1. The quarter in numbers
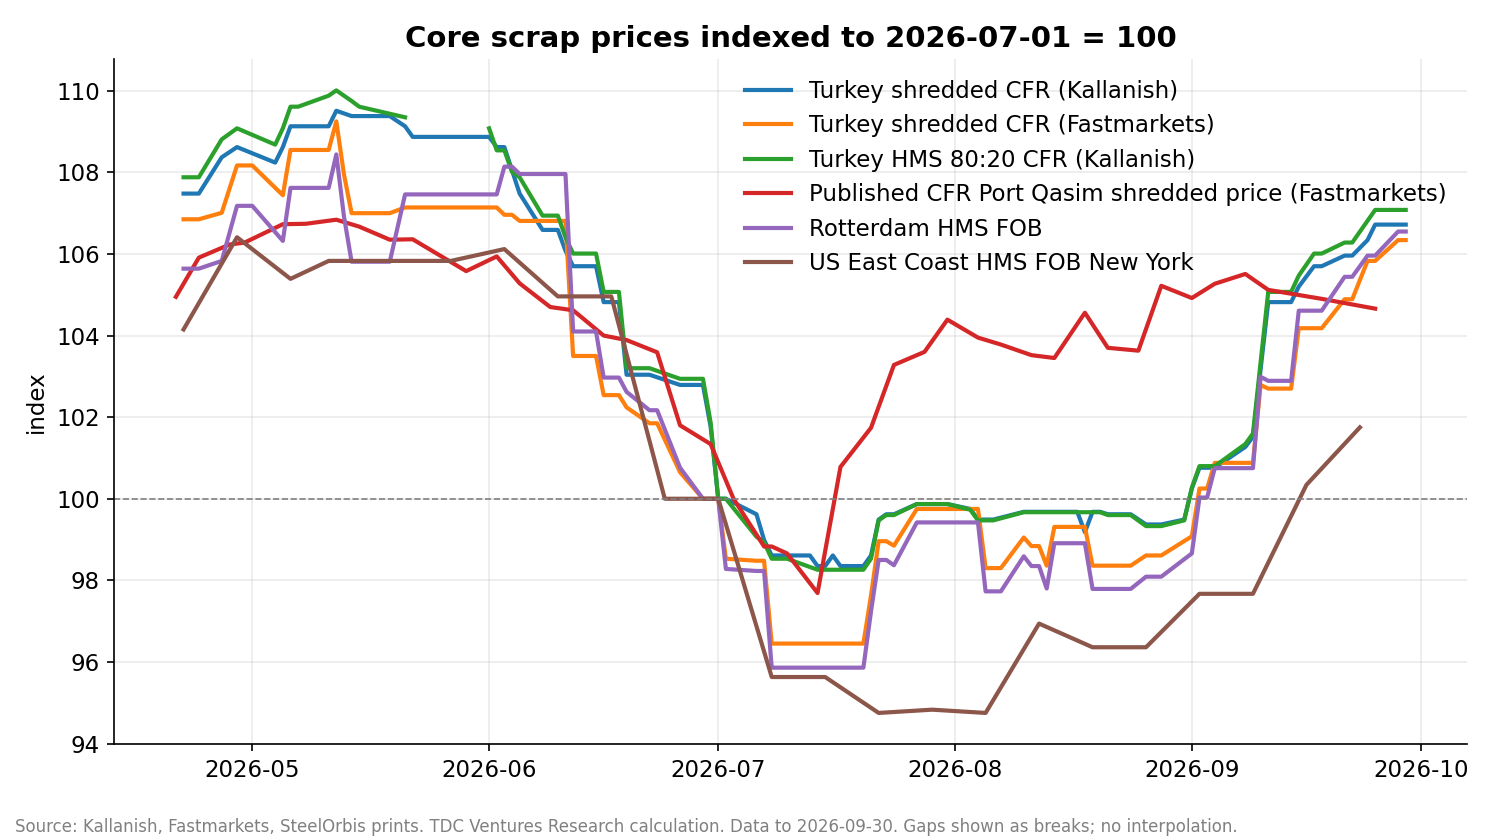 Chart 1 — core series indexed to the start of the quarter. Gaps shown as breaks; no interpolation.
| Series | 30 Sep level | Quarter change | % | Quarter high / low | Prints |
|---|---|---|---|---|---|
| Turkey shredded CFR (Kallanish) | $421.00 (29 Sep) | +$19.50 | +4.86% | $421.00 / $388.00 | 58 |
| Turkey shredded CFR (Fastmarkets MB-STE-0095) | $419.19 (29 Sep) | +$25.00 | +6.34% | $419.19 / $380.21 | 61 |
| Turkey HMS 1&2 80:20 CFR (Kallanish) | $401.00 (29 Sep) | +$19.50 | +5.11% | $401.00 / $368.00 | 56 |
| Published CFR Port Qasim shredded price (Fastmarkets MB-STE-0887) | $417.72 (25 Sep) | +$13.25 | +3.28% | $421.11 / $389.90 | 24 |
| Rotterdam HMS 80:20 FOB (Fastmarkets) | $359.28 (29 Sep) | +$22.09 | +6.55% | $359.28 / $323.23 | 61 |
| UK HMS 80:20 FOB (Fastmarkets, weekly) | $360.05 (29 Sep) | +$16.08 | +4.67% | $360.05 / $327.65 | 61 |
| US East Coast HMS FOB New York (Fastmarkets) | $349.00 (23 Sep) | +$6.00 | +1.75% | $349.00 / $325.00 | 13 |
| Iron ore 62% Fe CFR China (SteelOrbis) | $95.00 (30 Sep) | −$4.10 | −4.14% | $102.80 / $94.70 | 39 |
| Turkey rebar FOB (SteelOrbis, range mid) | $627.50 (30 Sep) | +$37.50 | +6.36% | $627.50 / $570.00 | 39 |
| LME copper | $14,448 (30 Sep) | — | — | $14,730 / $13,606 | 55 |
| LME aluminium | $3,232 (30 Sep) | — | — | $3,374 / $3,143.50 | 55 |
| LME zinc | $3,871 (30 Sep) | — | — | $4,004 / $3,576 | 55 |
Quarter change = last print on or before 30 June to last print on or before 30 September, no interpolation. LME series begin 26 July in our store, so no quarter change is stated. Pakistan prints near-weekly (24 in the quarter); Turkey daily.
FX: USD/PKR 277.14 (−0.23% over the quarter); USD/TRY 49.00 (+5.04%); EUR/USD 0.8802 (flat). The lira’s 5% slide raised Turkish mills’ dollar cost of scrap in local terms even as the dollar price rose.
2. What changed
Turkey. The quarter had three phases. July ground to a floor — Kallanish shredded touched $388.00, the quarter low — on weak rebar export demand and freight and war-risk costs mills could not pass through. August was flat and quiet. From late August the whole complex re-rated: a single-day Fastmarkets revision on 10 September (+$7.55 across four Turkish and European legs at once), Kallanish +$6.50 the next day, and then a grind to $421.00 by 25 September. The Kallanish shredded-over-HMS premium held at exactly $20.00/t for the entire quarter (93 aligned observations) — shredded tracked HMS dollar for dollar; it did not move on its own. Rebar FOB rose $37.50 to $627.50 alongside, so mills’ margin was not squeezed by the scrap move.
Pakistan. The published CFR Port Qasim shredded price (Fastmarkets’ index — the Pakistan reference price throughout this report) began the quarter at the low end of its band, reached $421.11 on 8 September, and then eased for three consecutive Friday prints to $417.72 while Turkey was still rising. Buyer bids stayed in the $415–420 area throughout September; the $440–445 supplier offers reported in the same weeks never produced a confirming sale on any public source we track. Our own forecasts on this market in September all landed in range precisely because they declined to chase the offer side.
Origins. Rotterdam HMS FOB rose $22.09 and UK HMS FOB $16.08 — both broadly matching Turkey’s move, as a Turkey-fed origin should. The US East Coast FOB New York index rose only $6.00, and printed just 13 times in the quarter, so it is the least observed leg; we note that caveat wherever we use it below.
Context. Iron ore fell 4.1% to $95.00 while scrap rose — the fourth consecutive month of scrap/ore divergence we logged in the weeklies. In non-ferrous, the quarter ended with a sharp late-September slide in zinc (quarter range $4,004 → $3,576) and aluminium that no publisher attributed to a named driver.
3. Why it changed
Our reading of the causal chain, link by link:
- Turkish mill restocking for October shipment (named by Kallanish on 1 September) created demand that coincided with the 10–11 September step up. Evidence: both Turkish shredded legs and HMS moved within two sessions of each other; rebar FOB rose in step, consistent with mills passing cost through.
- Origin prices followed, not led. Rotterdam FOB moved on the same sessions as Turkey CFR rather than twelve days ahead, as our entity page’s nominal lag suggests it should. That is evidence that the move was demand-pulled from Turkey, not supply-pushed from Europe.
- Pakistan did not follow because its own demand was weak. Fastmarkets’ narrative for the last two weeks of September describes slow finished-steel demand and falling buyer bids. Our September board shows New York–Qasim freight flat at $980 per 20FT, so freight cannot be the explanation for Pakistan’s flatness in this quarter.
- Currency amplified Turkey’s cost. USD/TRY +5% in the quarter; the lira-denominated scrap cost rose roughly 10% while the dollar price rose 5%.
We label link 3 likely rather than confirmed: it rests on the publisher’s narrative plus the absence of converting offers, not on a transaction-level dataset. That dataset is what we have begun collecting (see Methodology).
4. Structural or cyclical?
- Turkey’s rally: cyclical. A restocking-driven move of the kind this market has produced in prior quarters, with the shredded/HMS premium locked and rebar moving in step. Nothing in the quarter’s data supports a stronger word.
- Pakistan’s flatness: not yet classifiable. Five months of dual-benchmark history is below the twelve months we require before using “structural” about a relationship. We record the hypothesis (Section 6) and the test, and we will not upgrade the language until the data allows it.
- Scrap/iron-ore divergence: cyclical, watched. Four months is suggestive; it is also a period in which Chinese crude steel output fell 3.7% year-on-year in August (worldsteel) and Chinese raw-material demand weakened for its own reasons.
5. Between FOB and CFR — origin economics into Port Qasim
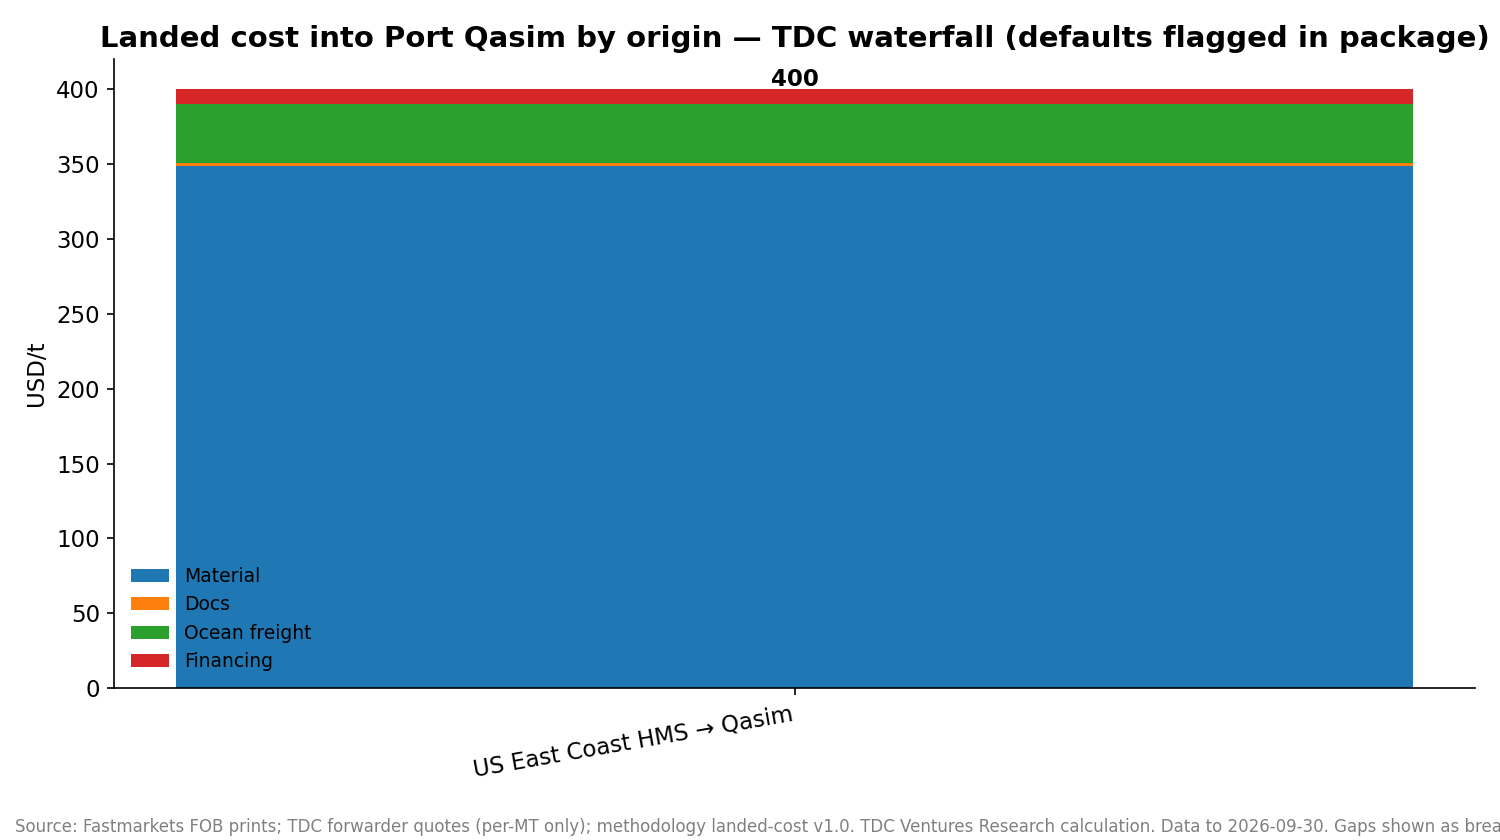 Chart 3 — landed-cost waterfall; lanes without an executable freight quote are not drawn.
This is the calculation this desk exists to make. Scrap into Pakistan moves in 20FT containers, so every Pakistan landed cost here uses the 20FT at 25 t. Using September prints and September forwarder quotes, our landed-cost engine gives:
| Origin | Material (FOB) | Ocean freight + surcharges / t | Docs | Financing (60 d, 12%, published assumptions) | Landed, USD/t | Freight share |
|---|---|---|---|---|---|---|
| US East Coast (New York) — HMS, 20FT | $349.00 (23 Sep) | $39.20 at 25 t | $2.00 | $9.84 | $400.04 | 9.8% |
| UK — HMS | $360.05 (29 Sep) | no TDC freight quote on file for the lane in Q3 | — | — | not computed | — |
| NW Europe (Rotterdam) — HMS | $359.28 (29 Sep) | no TDC freight quote on file for the lane in Q3 | — | — | not computed | — |
Three things follow. First, US East Coast HMS landed at roughly $400 against a published CFR Port Qasim shredded price of $417.72 — an $18/t gap before any quality adjustment between HMS and shredded, which is the arithmetic behind the US corridor’s growing share (US Census: $47.9 million of US ferrous scrap to Pakistan in June 2026 alone). Second, freight was the smallest part of the story this quarter: $39 a tonne on a $400 landed cost, and flat month-on-month. Third, we publish the UK and European rows as not computed rather than estimated: our landed-cost rule is that a lane without a dated, executable freight quote gets no number. Those rows fill in as the quotes are logged.
Payload and financing are TDC’s published default assumptions (25 t per 20FT — the Pakistan box; 30% advance 75 days, balance 60 days, 12% p.a., 0.4% bank fees). Change them and the landed number moves by a few dollars; it does not change the ranking.
6. Pakistan vs Turkey — the relationship under test
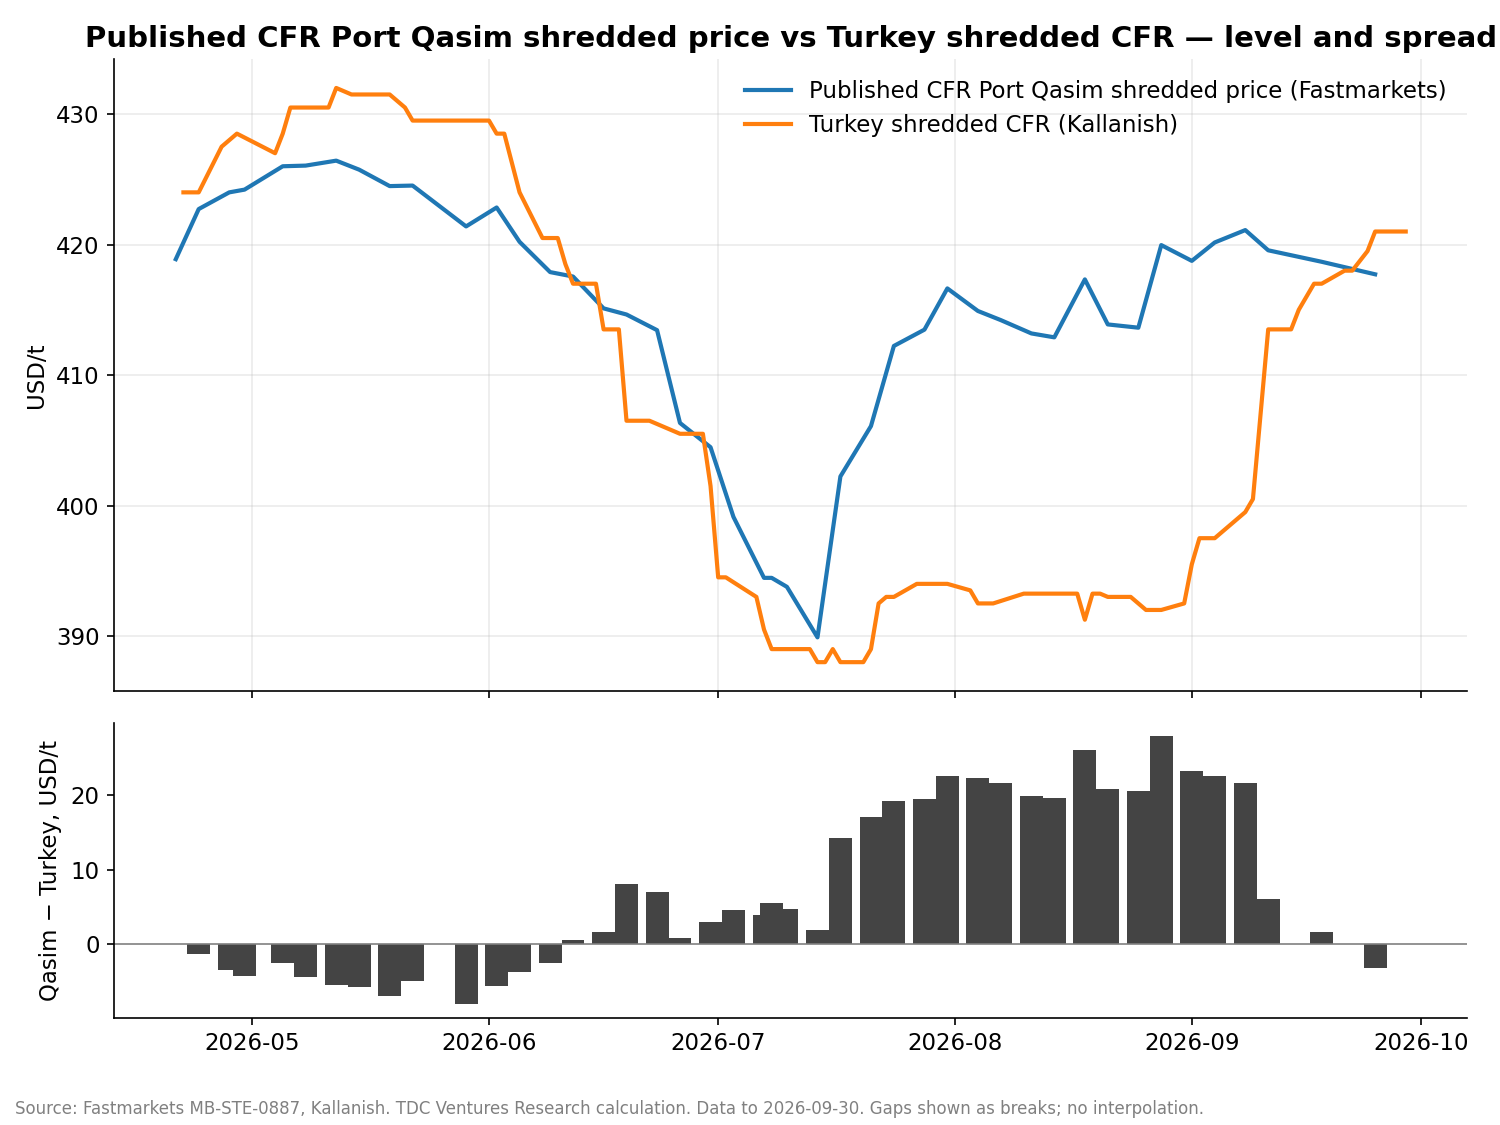 Chart 2 — the two shredded benchmarks and the Pakistan-minus-Turkey spread, last-observation aligned.
For most of this desk’s history, Turkey’s bulk HMS/shredded benchmark has been treated as the reference South Asian containerized prices follow with a lag. The third quarter is the first in which that assumption can be tested rather than assumed:
- The spread (published CFR Port Qasim shredded price minus Kallanish Turkey shredded) ran from about +$27 in mid-August to −$3.28 on 25 September — 43 aligned observations, no interpolation, last-observation alignment with zero staleness at quarter end.
- Across the four September weeks in which Turkey rose $19.50, Pakistan’s weekly prints moved +$1.41, −$1.55, −$0.88 and −$0.96. Direction agreed in one week of four.
- Freight on the main US lane was flat; USD/PKR was flat (−0.23%). Neither offset Turkey’s move.
Our working thesis (internal reference THS-2026-00001) is that Pakistan containerized shredded is currently priced off executable bids and local demand rather than off Turkey. The competing explanations we have not eliminated: a 2–4-week lag that would show up in October; the Qasim assessment’s weekly cadence hiding co-movement; or a one-off decoupling that closes as Pakistan restocks. What would change our mind: a 26-week directional agreement above 70% between the two series once that history exists, or Pakistan prints tracking Turkey’s October move within three weeks. The full test is the subject of our next Research Note.
7. What it means for you
Buyers (Pakistan mills and importers). The assessment has tracked concluded deals, not offers, all quarter. Buying at the physical anchor ($415–418) with an executable bid behind you has been the right posture and nothing in the data says it has changed. The one thing that would change it is a demand pickup of your own — if finished-steel offtake improves into the construction season, the $440 offers will start converting and the anchor moves. Watch your own order book before you watch Turkey.
Sellers and yards (UK, Europe, US East Coast). Your FOB rose with Turkey; Qasim did not follow. Quoting South Asia off the Turkish rally produces offers that sit unsold — four weeks of evidence. The competitive reference into Pakistan is landed US East Coast HMS at about $400/t. A European or UK shredded tonne has to land near that, after freight and finance, to clear; on September freight the arithmetic is tight, and October’s freight step makes it tighter for every origin.
Traders and indenters. The margin this quarter sat in origin selection, payload and payment terms, not in the destination price. Freight was the quiet variable and is now the live one: October’s New York–Qasim 20FT sheet is +$65 per box (+$2.60/t). Re-confirm validity on every open CFR quote before fixing October shipment.
Forwarders and logistics. Container demand on the US East Coast–South Asia lanes held through a quarter when the destination price did not rise — volume followed landed arithmetic, not headline prices. If Q4 brings the Pakistan restock the base case does not assume, the lanes that tighten first are the ones that were cheapest in September.
8. Outlook for Q4 2026
Scenarios — likelihoods are qualitative by policy; we do not publish probabilities we cannot defend.
| Base case | Bull case | Bear case | |
|---|---|---|---|
| Assumptions | October restocking in Turkey fades; mills covered; rebar export demand soft into the EU safeguard change; freight flat; Pakistan demand slow into the construction season’s late start | Fastmarkets lifts its Turkish legs again in October as it did on 10 and 21 September, and Pakistan buyers restock ahead of the construction season | Turkish rebar demand falls further, mills step back; Pakistan bids drop on weak finished-steel offtake; iron ore’s slide pulls the ferrous complex |
| Turkey shredded CFR (Kallanish) | $412–428, plateau | $425–440 | $395–410 |
| Pakistan shredded CFR Qasim | $410–422, range-bound | $422–435 | $400–412 |
| Rotterdam HMS FOB | $350–365 | $365–380 | $335–350 |
| Likelihood | moderate | low–moderate | low–moderate |
| Invalidation trigger | a Kallanish Turkey print above $428 or below $412 by 31 October | no further Fastmarkets step-up by 20 October | Turkey rebar FOB holding above $620 through October |
Horizon calls. The 30/90/180-day calls for Turkey shredded, Turkey HMS, Pakistan shredded, Rotterdam FOB and US East Coast FOB are registered one at a time under our published scoring rules and appear on the Track Record page from the day they are registered, not before. Until then this page carries scenarios, not calls.
The 180-day view for Pakistan is deliberately wide: it spans the EU waste-shipment consultation outcome (16 October) and the first visibility of any 2027 supply redirection, neither of which we can size yet.
9. Risks to the view
Upside: a further Fastmarkets step-up on the Turkish legs (it happened twice in September); Turkish mill demand for November shipment arriving earlier than the base case assumes; a Pakistan restocking wave once the government’s bill relief question resolves. Downside: rebar export weakness into the EU safeguard regime; Chinese output (−3.7% y/y in August per worldsteel) and iron ore’s slide transmitting to scrap via billet; Hormuz-related freight and war-risk costs re-widening; and, for Pakistan specifically, a Fastmarkets assessment that now prints only weekly, which raises the chance that a genuine move is reported late.
10. Our record this quarter
We publish every forecast before the outcome, with the rule for scoring it fixed in advance, and we score it on the first publisher print on or after the target date. The quarter’s resolved calls on the two core markets:
| Market | Target | Range (central) | Actual | Verdict | Error vs central |
|---|---|---|---|---|---|
| Turkey HMS 80:20 CFR | 17 Jul | $362–370 (366) | both legs in range | HIT | — |
| Pakistan shredded CFR Qasim | 17 Jul | $385–394 (390) | target-date print above range | MISS (re-scored 20 Jul from an interim HIT) | > $10 |
| Turkey shredded CFR | 6 Aug | $390–400 (395) | K $392.50 / FM $387.50 | PARTIAL | −$2.50 / −$7.50 |
| Pakistan shredded CFR Qasim | 6 Aug | $406–420 (413) index leg | $414.21 | HIT | +$1.21 |
| Pakistan shredded CFR Qasim | 4 Sep | $408–418 (412.5) | $420.16 | MISS | +$7.66 |
| Turkey shredded CFR | 4 Sep | $386–396 (391) | K $397.50 / FM $397.64 | MISS (both legs) | +$6.57 avg |
| Turkey shredded CFR | 11 Sep | $391–401 (396) | K $413.50 / FM $404.84 | MISS (both legs) | +$13.17 blended |
| Pakistan shredded CFR Qasim | 11 Sep | $408–423 (415) | $419.56 (FM); Kallanish leg unscoreable | HIT | +$4.56 |
| Turkey shredded CFR | 18 Sep | $397–413 (406) | K $417.00 / FM $410.66 | PARTIAL | +$11.00 / +$4.66 |
| Pakistan shredded CFR Qasim | 18 Sep | $415–428 (420) | $418.68 | HIT | −$1.32 |
| Turkey shredded CFR | 25 Sep | $408–424 (416) | K $421.00 / FM $417.19 | HIT (both legs) | +$5.00 / +$1.19 |
| Pakistan shredded CFR Qasim | 25 Sep | $414–426 (420) | $417.72 | HIT | −$2.28 |
Three dark-market calls (Pakistan PNS, rails and windmill plates) lapsed with no qualifying transaction inside their windows and are excluded from every statistic, as our rules require; one copper cash/3M spread call hit its range with a large magnitude error that we report separately because spread errors and price errors are different units. Two Kallanish Pakistan legs closed unscoreable because that publisher stopped printing the series — logged, not scored, never substituted.
The book as of 2 October: 15 of 24 scored components in range (62.5%); September alone 5 of 11, mean absolute error $6.89/t. September was the hardest month: every Turkey miss was on the high side during a rally we identified but under-estimated. We have adjusted how we weight an identified driver that has already shown itself once in a cycle; the test of that adjustment is the Q4 record, published as it resolves. The full record — every range, actual and error, misses included — is on the Track Record page.
11. What would change our mind
- On the Turkey plateau: two consecutive Kallanish prints above $428 before 20 October.
- On Pakistan’s independence from Turkey: Qasim shredded tracking Turkey’s October direction within three weeks on at least three of four prints.
- On US East Coast competitiveness into Qasim: a New York–Qasim 20FT rate above $1,200 sustained for a month (roughly +$9/t at 25 t, which would erase half the gap to the index) — see the post-cutoff note below.
- On the scrap/ore divergence: iron ore back above $100 with scrap flat.
12. Watch next
| Item | Current (30 Sep) | Why it matters |
|---|---|---|
| Kallanish Turkey shredded CFR | $421.00 | plateau vs extension; invalidators above |
| Published CFR Port Qasim shredded price — Fastmarkets, Fridays | $417.72 | the Pakistan reference; the test of Section 6 |
| New York → Port Qasim 20FT (TDC board) | $980 | freight share of landed |
| Rotterdam HMS FOB | $359.28 | origin pass-through |
| EU non-OECD waste-export consultation | closes 16 Oct | 2027 supply redirection |
| USD/PKR | 277.14 | buyer purchasing power |
| Iron ore 62% CFR | $95.00 | ferrous complex driver |
Post-cutoff note (received after 30 September, not used in the figures above): TDC’s October freight board shows New York–Qasim at $1,045 per 20FT (+6.6%). On the engine’s assumptions that adds about $2.60/t to US East Coast landed cost. We will treat it in the October review.
13. Methodology and coverage
Coverage label: Moderate. Turkey legs: daily, two publishers, 56–61 prints each. Pakistan: the published CFR Port Qasim shredded price is Fastmarkets’ index (MB-STE-0887), treated as the authoritative Pakistan reference throughout; one publisher, weekly from 11 September, 24 prints. Pakistan freight and landed figures use 20FT containers, the box Pakistan-bound scrap ships in. US East Coast FOB: 13 prints. Freight: TDC’s own forwarder quotes, US East Coast and Gulf lanes only; UK and European lanes not yet on file. Internal bid/offer observations: collection began this quarter and no aggregate is published until a sample of at least three observations from two or more counterparties exists for a week.
Calculations: period changes use the last observation on or before each boundary; spreads align on the last observation of the second series on or before each date and record staleness; the landed-cost waterfall is published in full at intel.tdcventures.com/research/methodology (payload 25 t per 20FT for Pakistan; financing 30% advance 75 days, balance 60 days, 12% p.a., 0.4% fees; origin docs $2/t). Every number in this report resolves, in our internal manifest, to a calculation identifier and the observations behind it. Forecasts are scored on publisher prints only; analyst commentary never resolves a call.
Sources. Kallanish Steel (Turkey, Bangladesh, iron-ore prints); Fastmarkets Steel Scrap Daily (MB-STE-0095, 0417, 0887, 0420, 0418, 0100); SteelOrbis (Turkey HMS range, rebar, iron ore); metals.dev LME spot; fawazahmed0 currency-api; worldsteel August 2026 production; US Census Bureau June 2026 HS-7204 exports; USGS Mineral Industry Surveys December 2025; TDC Ventures forwarder quotes (per-tonne only). Prices are quoted single values with attribution under licence; no publisher data is redistributed.
TDC Ventures trades and indents ferrous and non-ferrous scrap in the markets discussed here, including the Pakistan and Turkey corridors. Conclusions follow the evidence and methodology stated. This is market research, not trading advice; indicative prices are not offers; forecasts are scored estimates and may be wrong — our record is published in full at the Track Record page.